
Don’t just throw in one number. Play God with your finances. Try a £250,000 house, then a £300,000 one. See how the costs swell. It’s like a video game where you lose money instead of lives. Change the deposit percentage from 5% to 10% and watch the monthly mortgage payment shrink—it’s oddly satisfying.
Always run the numbers with a fixed-rate mortgage for two or five years. The calculator shows your monthly outgoings, but also the total cost over the term. That’s where the real shocker lives. A £1,200 monthly payment sounds fine until you see it adds up to £360,000 over 25 years.
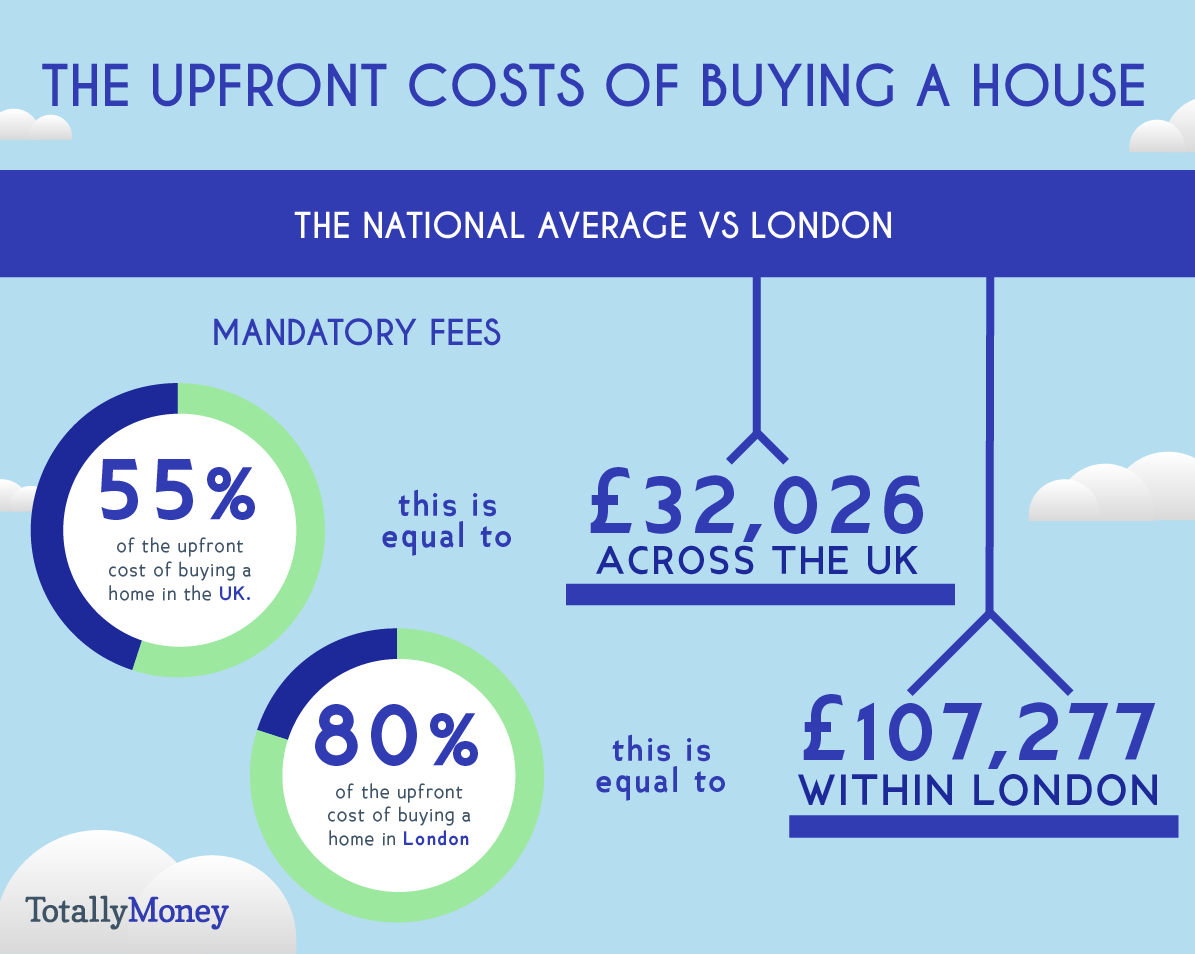 The Real Cost of Buying Your Own Home | TotallyMoney
Pro tip: Use a calculator that factors in rising interest rates. The Bank of England base rate has a habit of ruining parties. A 2% rate hike can add £300 to your monthly bill. That’s your Netflix, coffee, and takeaway budget, gone.
Cultural Footnotes for the Aspiring Homeowner
Remember that episode of Friends where Monica becomes obsessed with the perfect apartment? That’s you, but with spreadsheets and a soggy Yorkshire. In the UK, we measure success by square footage proximity to a Waitrose. The calculator helps you afford the Waitrose.
Also, Brits love a good rule of thumb: aim for a mortgage no more than 4.5 times your annual salary. If you earn £40,000, that’s a £180,000 mortgage. A calculator will cross-check this and call you out if you’re dreaming beyond your means. It’s the friend who says, “You’re not wearing that, are you?”
And here’s a fun little fact: the average UK house price hit £285,000 in 2026. But that masks huge regional differences. In Yorkshire, you get a terrace house with a garden. In London, you get a parking space with a view of a bin. A good calculator lets you adjust your location, so you don’t cry over postcode envy.

