High limits are like a pet tiger—impressive, but you need rules. If you max out a $30,000 card, your credit score takes a nosedive. And the interest? At 22% APR, a $30,000 balance costs you $550 a month in interest alone. That’s rent money vanishing into thin air.
But here’s the playful catch: if you’re smart, you can use the high limit to game the system. Carry a tiny balance (under 10% of the limit), pay it off, and watch your credit score jump like a kangaroo on caffeine. It’s a loop of free reward points and better rates.
 What Is Level Credit Card at Pauline Dane blog
How to snag one (without selling a kidney)
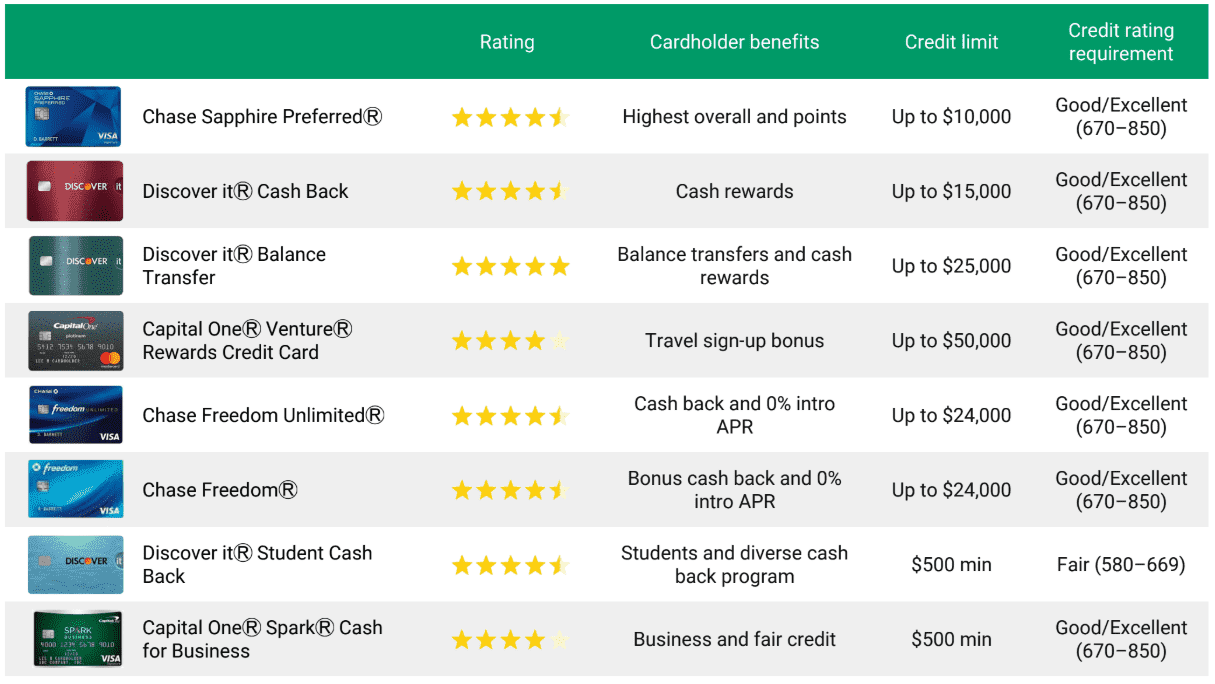
First, stop applying for every card you see. Hard inquiries hurt your score. Instead, ask your current bank for a limit increase. They know you. If they say no, try a premium card like Chase Sapphire Preferred or Capital One Venture X. These start at $10,000 limits if you’ve got solid credit.
Pro tip: Report your full income, including side hustles, investments, or that Etsy shop selling llama-shaped candles. Banks love seeing high income. They’ll slap a bigger limit on your card faster than you can say "interest rate."

