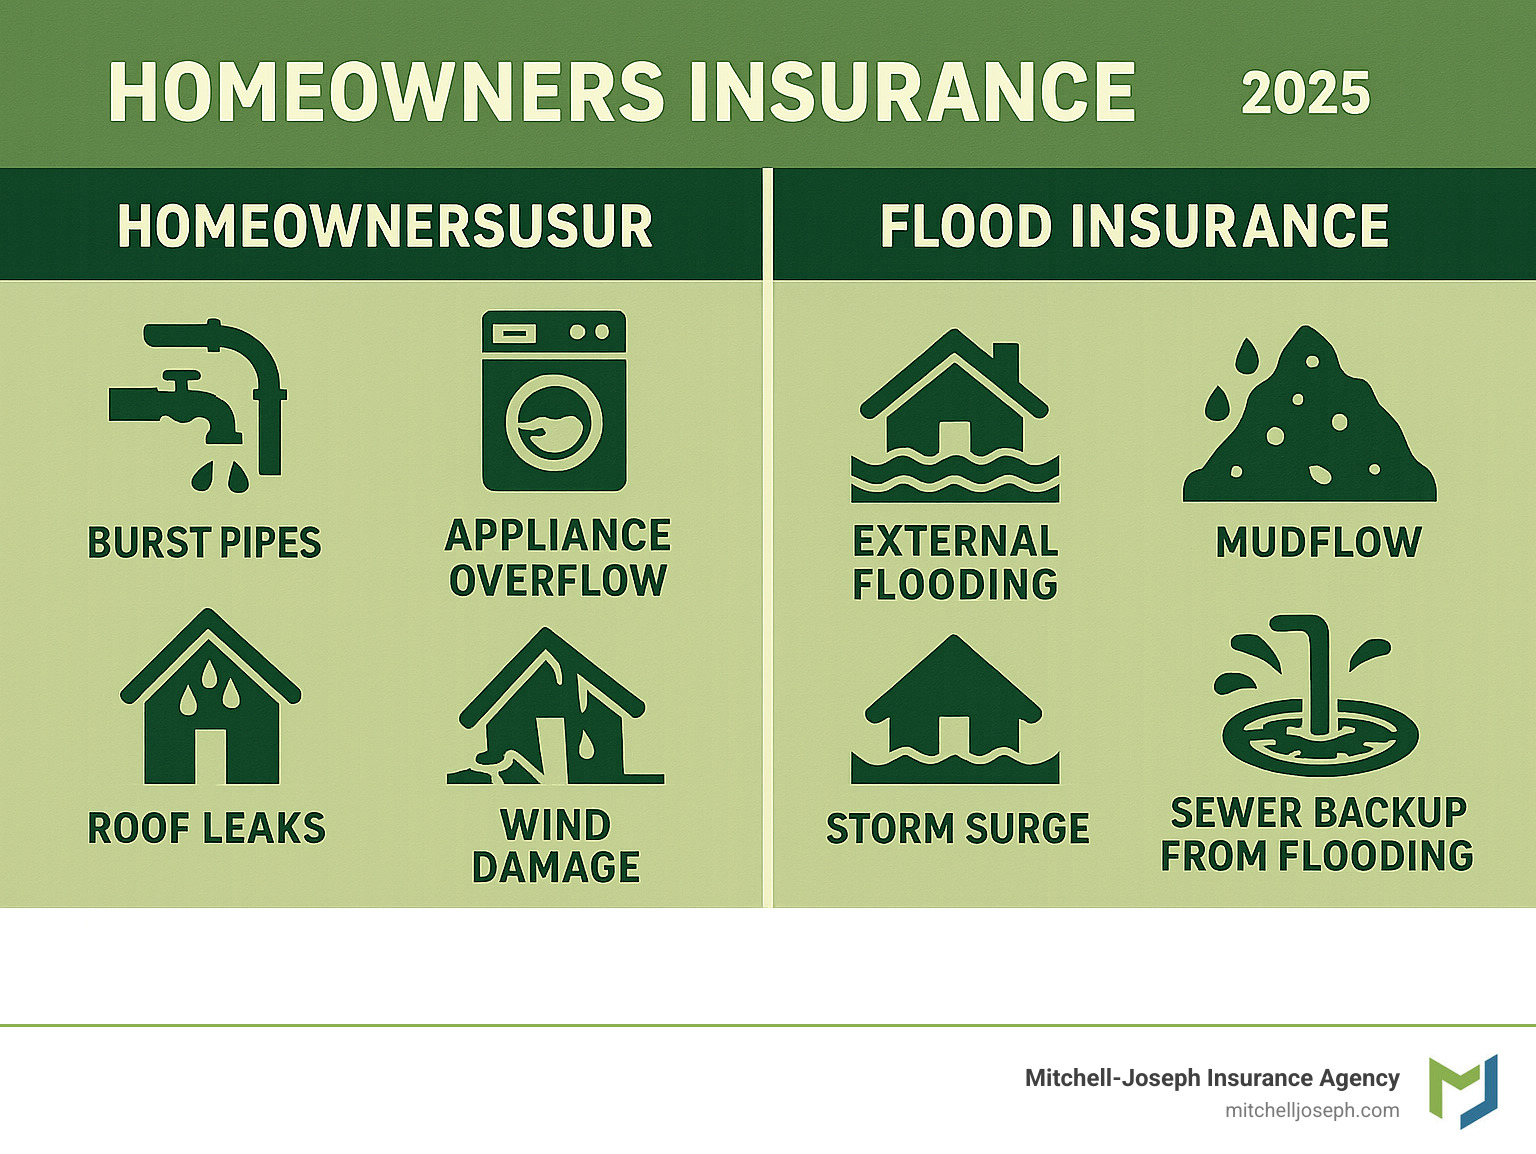
Here’s the core twist: standard homeowners insurance is a bit like a picky eater. It loves covering sudden, unexpected water damage, like a burst pipe or a leaky roof from a windstorm. That’s totally on the menu.
But flooding from outside—like a raging river, a storm surge, or relentless rain that seeps through your foundation—that’s a different creature entirely. Most standard policies treat this like uninvited guest who broke the door down and refuses to pay for repairs.
Think of it this way: your insurance is happy to clean up a spilled soda inside the house. But if the whole soda factory exploded next door and flooded your block? That’s a whole different policy—often called flood insurance—and you have to buy it separately.
Why Is Flooding Treated Like the Black Sheep?
It’s not because insurance companies are mean. It’s because flooding is weirdly common and catastrophic. The risk is so high and so widespread that regular home insurers would go broke trying to cover everyone. So, they politely say, “Nope, that’s a special club.”
This is where the National Flood Insurance Program (NFIP) steps in, like a government-sponsored safety net. It’s basically a federally backed plan that lets you buy flood coverage, usually through the same agent who sells your home insurance. Kind of like ordering a burger and being told the fries are extra—but those fries could save your whole meal.
Interesting, right? It’s not a secret plot; it’s just that water from the ground up is treated differently than water from the roof down. One is a plumbing party foul, the other is a neighborhood-wide event.
 Understanding Flood Insurance Michigan for Homeowners

