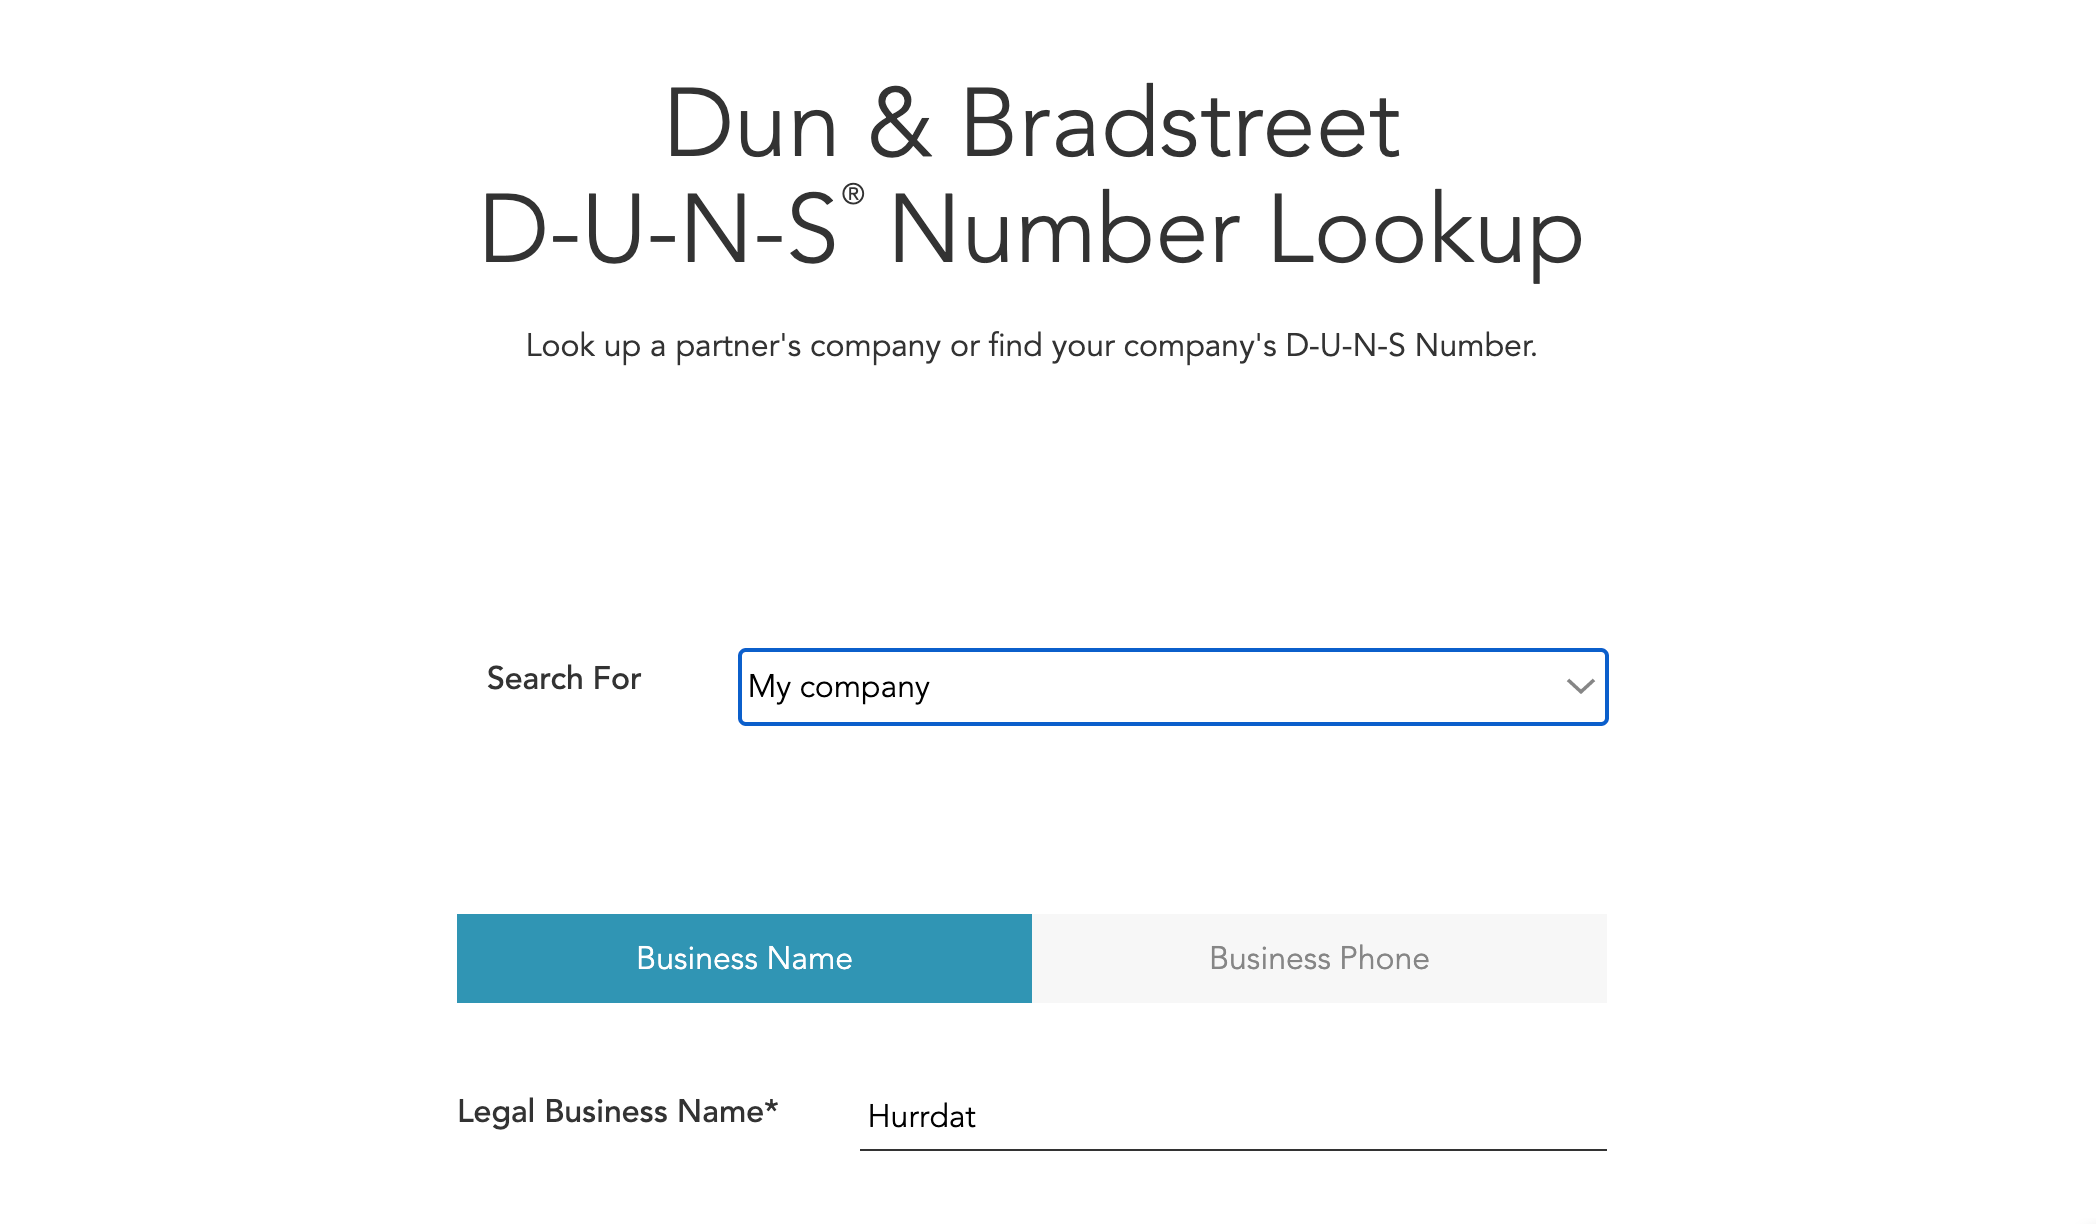
The easiest way is to head straight to D&B’s own website—it’s called “D&B Hoovers” or the “D-U-N-S Number Lookup” tool. Type in the nine digits, and boom: you get a business profile faster than you can say “liability.” Just be warned: the free version shows basic info. The juicy details (like full credit reports) usually cost a fee.
But here’s a life hack: if you’re looking up a public company, you can often find their D-U-N-S number on the SEC’s EDGAR database for free. (Yes, I’m that person who reads SEC filings for fun—don’t judge me.) You can also use Google with the search “D-U-N-S number 123456789”, which sometimes pulls up public records from government contracts.
 beryfoundry - Blog
Pro tip right here: which you’re on the D&B site, look for the “Match Confidence” field. If it says “High,” you’re golden. If it says “Low,” you might be looking at the wrong business—or a particularly successful fraudulent one.
What to Do When You Get the Results (The Fun Part)
When the report pops up, don’t just stare at the address. Check the credit rating—D&B uses a score from 1 to 100. Anything above 70? That’s a solid partner. Below 50? You might want to ask for a deposit upfront.
Also, look at the Payment History section. If it shows late payments to suppliers, your client might become their next victim. I once saved a friend from a “reliable” printer that had a habit of paying vendors after 120 days. That printer is now in a different line of work.

