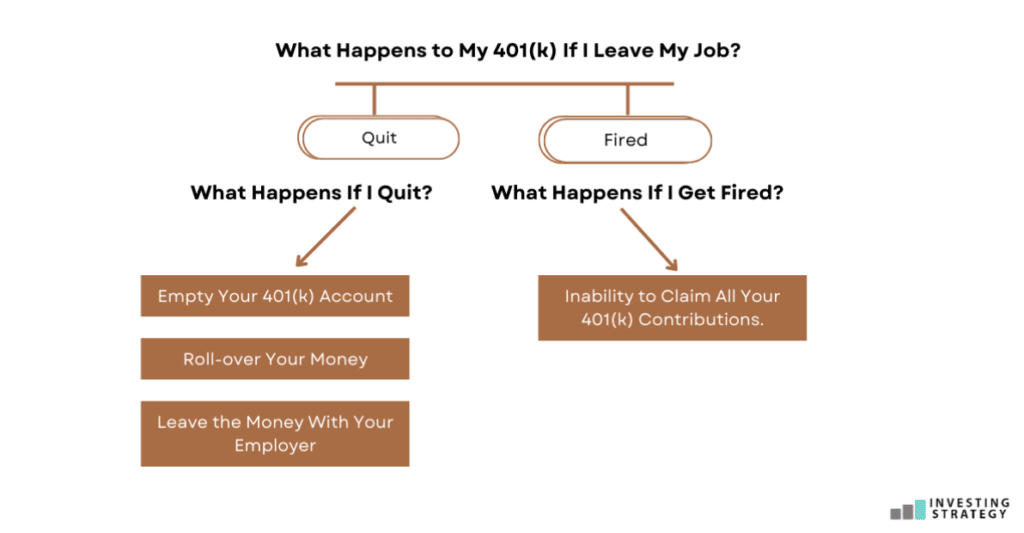
This is the “marry the two” option. You transfer the old 401k directly into your new employer’s plan—like a financial handshake. Sounds clean, right?
The perks: one account to manage, and you might get access to better investment choices. But read the fine print—some new plans have high fees or crappy fund options. You don’t want to trade bad for worse.
Pro tip: ask your new HR if they accept rollovers before you sign anything. And never make the check payable to you—have it go directly to the new plan. That little mistake can trigger a tax bomb.

