
If you’re married, the plot thickens—and gets warmer. In the U.S., federal law (ERISA) requires your spouse to sign off if you want to name anyone else as beneficiary for a defined benefit plan. It’s like a trust fall: your spouse automatically gets at least 50% of your pension as a survivor benefit, unless you both opt for a lower payout. Imagine you’re in a rom-com—your pension is the house, and your partner gets the keys (plus the mortgage-free vibe).
But here’s a practical tip: choose the “joint and survivor” option when you retire. It reduces your monthly check by about 5–10%, but it’s like buying insurance for your partner’s future. Think of it as a friends-with-benefits deal—but with your pension.
What About Your 401(k) or IRA?
Ah, the DIY pension—the cute little basket of stocks and bonds you built yourself. If you die, the full balance goes to your named beneficiary—no spousal drama, no limits. This is where you channel your inner Jeff Bezos: you can leave it to a charity, your best friend, or that cousin who always sends birthday memes. The catch? Your beneficiary must withdraw the money within 10 years (under the SECURE Act), or pay taxes like you’re buying a luxury handbag—slow and painful.
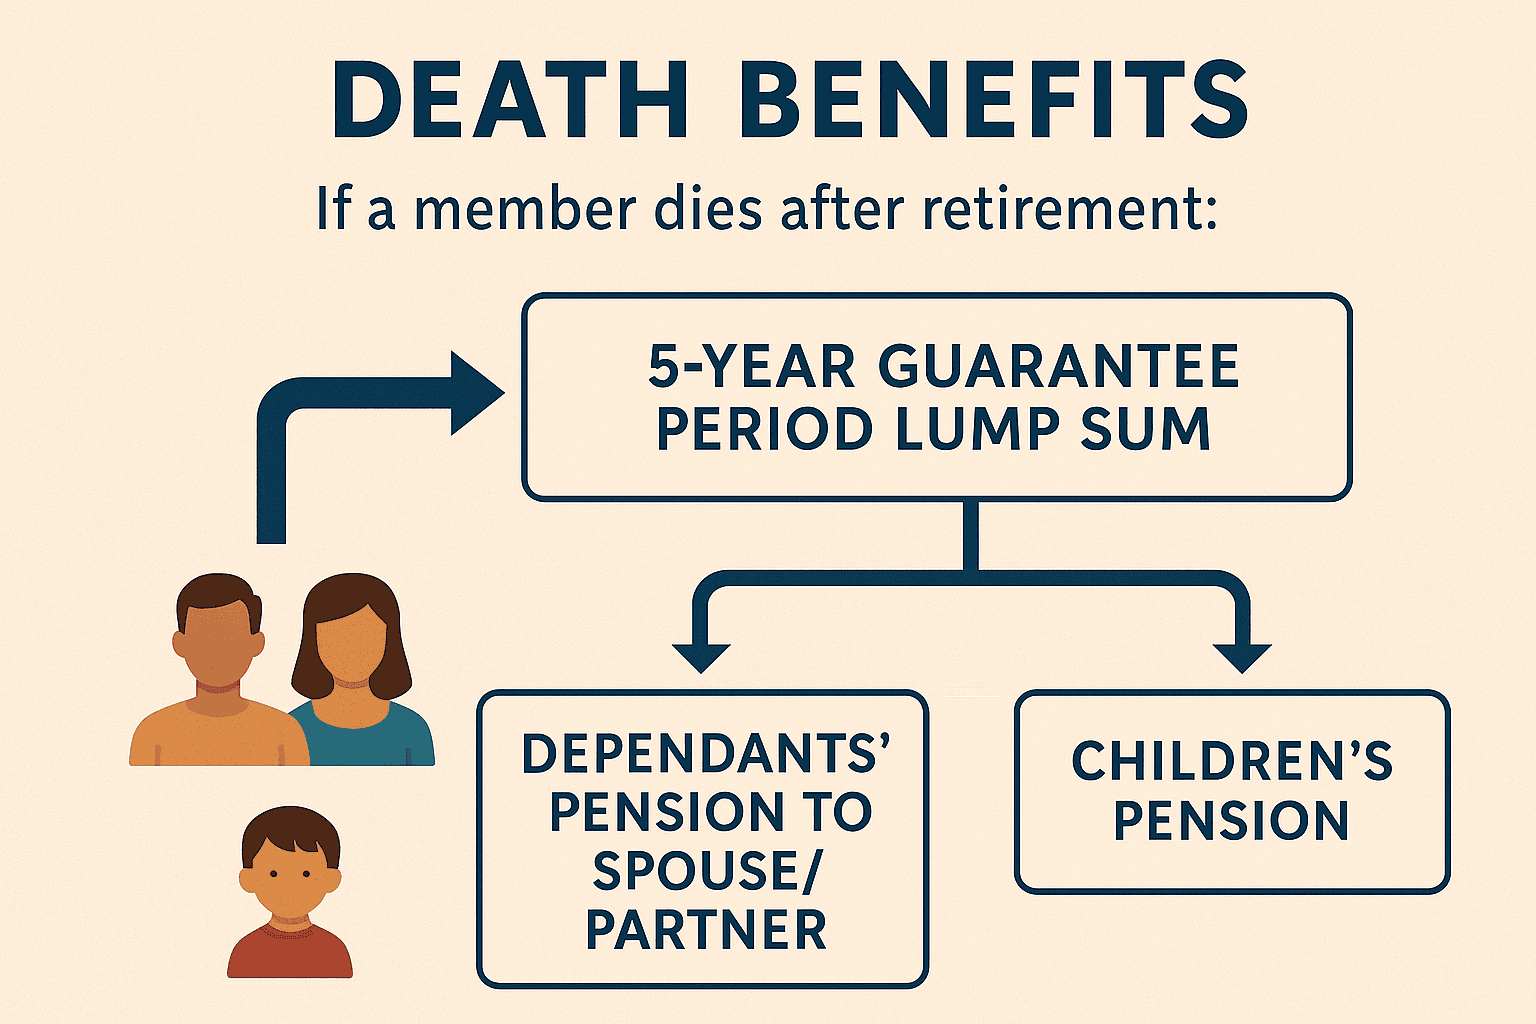 NHS Pension Contributions In 2026 : How Much Will I Get?
Pro tip: Update your beneficiary forms every time you get a new partner, a new cat, or a new tattoo. Divorced? Remarried? Your ex might still be listed, and that’s a plot twist worthy of a Netflix thriller.

